PulseCore Events
Digital Banking for SMEs: How Small Businesses Access Enterprise Banking Technology
Why SMEs remain underserved in digital banking
Small and medium-sized enterprises account for over 95 per cent of businesses globally, yet remain one of the most underserved customer segments in banking. Banks have invested heavily in retail experiences and complex corporate platforms, leaving SMEs caught between the two. Digital capabilities towards SMEs are approximately five years behind retail channels within the same institutions. This gap means small business owners often struggle with tools designed either for individuals or multinational corporations, neither matching their actual operational needs.
SME leaders are aware of this. When asked to rate their digital banking experience, 53 per cent say they are satisfied, yet 39 per cent report being very satisfied. More concerning for traditional banks: 10 per cent of SMEs in the UK, Belgium and the Netherlands have switched entirely to digital challengers, citing faster credit processing, better credit access, and improved digital capabilities as reasons.
What SMEs expect from digital banking platforms
Unlike retail customers with simple account access or large corporates with treasury teams, SMEs need platforms that integrate into their everyday business workflows. They expect three core principles: simplicity, automation, and actionable insights.
SME decision makers split into three groups: 20 per cent prefer pure digital channels, 20 per cent prefer human-only interaction, and 59 per cent want hybrid access. When using digital platforms, SMEs prioritise solutions for transaction management (50 per cent), customer support (47 per cent), and security (28 per cent). Beyond banking basics, they increasingly demand integrated accounting, customised reporting, and tools that sit outside traditional banking—such as expense tracking and cash flow forecasting.
Core capabilities: payments, cash flow, and automation
Real-time payments lie at the heart of SME engagement. Businesses need to move money instantly to suppliers, staff, and partners without branch hours or processing delays. Bulk payment processing lets finance teams execute multiple transactions in one step, cutting administrative burden. Multi-currency support matters as SMEs expand internationally.
Cash flow management is equally critical. Automated reconciliation matches incoming and outgoing transactions against invoices and accounting records without manual intervention. Real-time account access from mobile apps means business owners can check balances, execute transfers, and approve payments from anywhere. Many platforms now integrate directly with accounting software, reducing spreadsheet work and keeping tax estimates current.
Expense categorisation automatically sorts transactions into meaningful categories, helping SMEs understand spending patterns and control costs. Receipt management captures digital records for audit readiness. Budget planning tools let businesses set financial targets and adjust operations in real time. These capabilities transform banking from a back-office function into an operational tool that actively supports decision-making.
How enterprise banking technology scales for small teams
Enterprise-grade banking platforms now include features that make them accessible to small teams. Role-based access controls let business owners assign specific permissions to each staff member—one person can approve payments up to a set limit, another can view reports only, without anyone having full account access. This maintains control and security while distributing tasks.
Mobile-first design means SMEs can manage accounts on smartphones and tablets, not just desktops. Real-time transaction alerts notify business owners instantly of incoming and outgoing money, improving financial awareness and fraud detection. For businesses managing multiple accounts or entities, consolidated dashboards provide a single view of cash across all accounts, currencies, and card programmes.
The business case: speed, simplicity, and efficiency
Digital banking for SMEs streamlines operations. Faster payments improve working capital management. Easier access to credit—through digital onboarding and automated underwriting—means business owners can secure funding in days instead of weeks. Real-time visibility into cash flow prevents cash shortages and allows SMEs to maintain liquidity confidently.
Manual processes disappear. No more chasing paper statements, printing files for accountants, or reconciling transactions in spreadsheets. When connected to accounting platforms, digital banking reduces operational costs and frees time for SME leaders to focus on growing their business rather than managing its finances. Supporting data shows top-performing banks in the SME segment generate twice as much revenue per active customer as weaker performers, and nearly four times as much revenue per risk-weighted asset.
Digital identity and faster onboarding
Traditional business banking requires documents by post, branch visits, and weeks of processing. Digital identity verification and electronic signature technology compress onboarding to days. SMEs upload business registration documents and financial statements through secure digital channels. Automated know-your-customer and anti-money laundering screening validates business owners and authorised signatories instantly and accurately, reducing friction and fraud risk.
Instant eligibility checks let businesses understand available credit options before formally applying. Real-time application status updates—delivered through automated notifications—provide transparency and reduce support inquiries. Once approved, funds can disburse immediately through automated workflows, turning the banking relationship into a growth enabler rather than a constraint.
Learning from industry leaders
Leading banks designing SME-centric platforms emphasise three practices. First, they simplify interfaces to focus on the most relevant financial tasks, avoiding feature bloat. Second, they automate integration with the digital tools SMEs already use—ERP systems, accounting software, invoicing platforms—so data flows without manual entry. Third, they provide insights and forecasting, not just data. AI-powered recommendations now alert SME customers to risks (overdraft within 14 days), opportunities (revenue increase), and optimization points (spending relative to balance).
Banks serious about SME growth combine digital-first design with human expertise for complex interactions. Self-service handles routine tasks and basic products, reducing costs and speeding transactions. Real conversations with relationship managers focus on strategic decisions—tax changes, lending options, growth planning—where expertise adds genuine value. This hybrid model builds confidence and loyalty in a way neither pure digital nor pure human interaction alone can achieve.
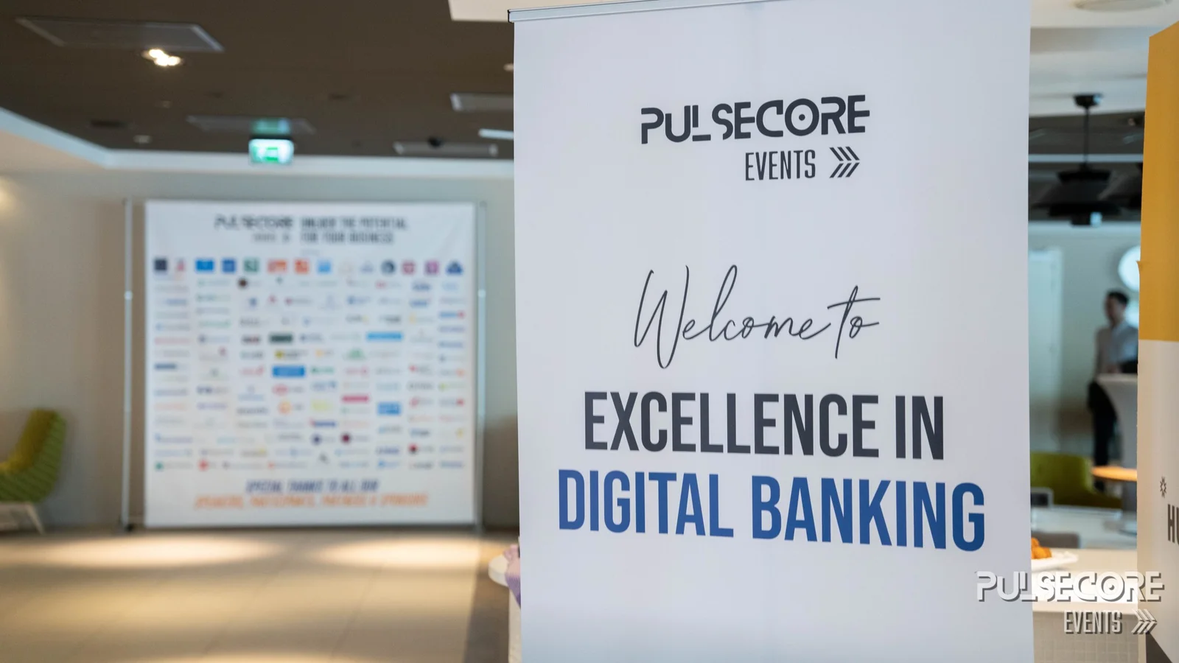
The Excellence in Digital Banking 7.0 International Summit brings together senior banking leaders and technology experts to explore how financial institutions are reshaping services around artificial intelligence, digital identity, and next-generation architecture. Running 25–27 November 2026 in Amsterdam with both in-person and online attendance options, the summit features sessions on building competitive digital platforms, managing risk in modern systems, and integrating fintech partnerships—all directly relevant to banks scaling SME capabilities. Review the three-day schedule to see talks on digital transformation, onboarding, and open finance from leaders across NatWest, BNP Paribas, Commerzbank, and other major European institutions. Financial innovators managing SME platforms will find peer insights on the architectures, talent strategies, and regulatory approaches driving results in this critical customer segment.
Frequently asked questions
Why is digital banking important for SMEs if they already use spreadsheets and traditional banks?
Spreadsheets introduce manual error, security risk, and time waste. Traditional banks treat SMEs as scaled-down versions of retail banking, ignoring operational complexity. Integrated digital banking automates reconciliation, prevents cash flow surprises, enables faster payments to suppliers, accelerates credit decisions, and surfaces insights that inform strategy. These capabilities let SME leaders spend time on growth rather than financial administration.
Does digital banking for SMEs cost more than traditional business accounts?
No. Many digital-first banks offer competitive or lower fees than incumbents because they operate at lower cost. Digital onboarding, self-service tools, and reduced support overhead allow banks to pass savings to SME customers. High fees and pricing remain the top reason SMEs switch to alternative providers, so digital banks competing for this segment typically price aggressively to win share.
Is digital banking secure enough for business accounts?
Yes. Modern platforms use multi-factor authentication, end-to-end encryption, role-based access controls, and real-time fraud monitoring. Regulatory compliance requirements (KYC, AML, PSD2) enforce rigorous security standards. In many cases, digital-first banks implement stronger security than legacy systems because they were built for modern threats rather than adapted from older architecture. Regulatory deposit protection schemes (FSCS in the UK, equivalent schemes across Europe) cover eligible business accounts.
Can SMEs still speak to someone if they need help with complex decisions?
Yes. The best digital banking platforms combine automation with access to relationship managers or specialists for complex questions. Self-service handles payments, reporting, and routine inquiries through chat or phone support. Strategic questions—tax planning, lending structure, working capital optimization—benefit from expert guidance. This hybrid model reduces costs while preserving the human element for decisions that matter.