What is Composable Banking
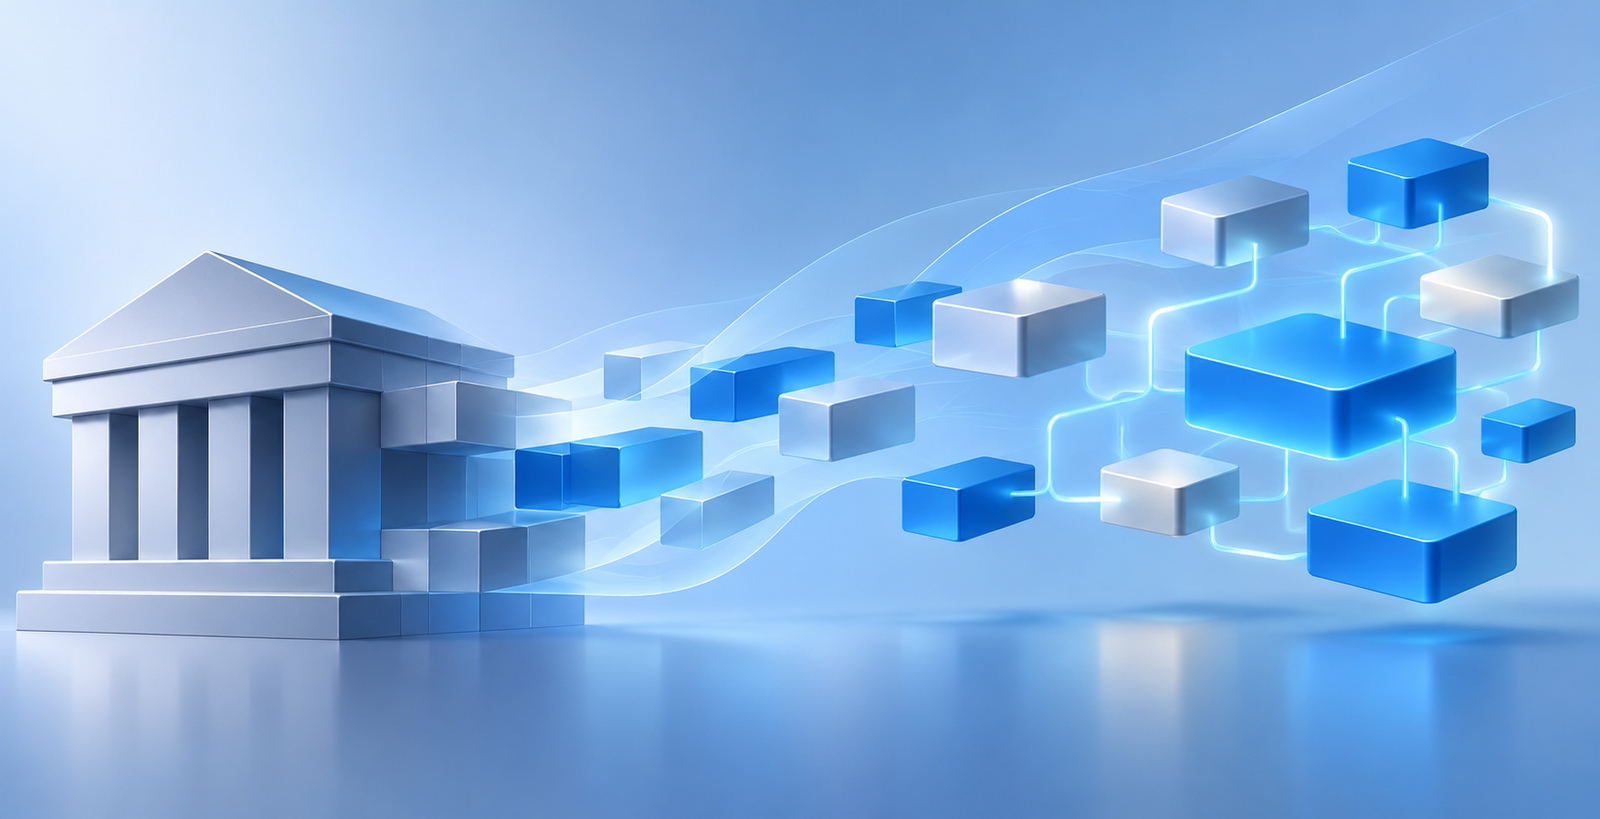
Composable banking is a modular architecture model in which financial institutions replace monolithic, tightly coupled core systems with independent, API-connected components that operate as a coordinated whole. Each module—lending, payments, customer onboarding, KYC, fraud detection—can be developed, deployed, and scaled independently without triggering system-wide changes.
Unlike traditional banking platforms, where business logic and customer channels are locked into a single vendor's suite, composable banking embraces openness and flexibility. Banks select the best-of-breed component for each function and integrate them through standard APIs, giving technical and business leaders the agility to adapt and innovate on their own terms.
Composable vs Modular vs Monolithic
The terms are often confused, so clarity matters. Monolithic systems concentrate all product logic, channels, and operations in a single, integrated platform—fast to build initially, slow and risky to change. Modular banking uses predefined, proprietary modules that extend a core system, but those modules are often tightly bound to the vendor's ecosystem. Composable banking, by contrast, treats each component as truly independent, connected through open APIs and event-driven messaging. This independence is the critical difference: it eliminates vendor lock-in and lets teams move at business speed, not at the pace of a core refresh cycle.
Why Banks Move From Monolithic to Composable Architecture
Legacy core banking systems were built for consistency and stability, not for the speed, integration, and experimentation that modern digital banking demands. A monolithic core often becomes a bottleneck: product teams must wait for core releases, even minor changes trigger cross-system testing, and innovation cycles stretch to months or years.
Composable architecture solves this by decoupling systems. New digital capabilities—a real-time payment service, an AI-powered onboarding workflow, a loyalty programme—can be deployed as independent modules without touching the core. Teams work in parallel, each owning their own service domain, while orchestration ensures coherence across the bank.
This separation also reduces deployment risk. Instead of a risky big-bang cutover, banks can test new modules in isolation, validate business impact, and roll back without affecting production. According to research highlighted at industry banking summits, banks adopting composable architectures report faster product launches and significantly lower technical debt than those maintaining monolithic cores.
Key Architectural Layers of Composable Banking
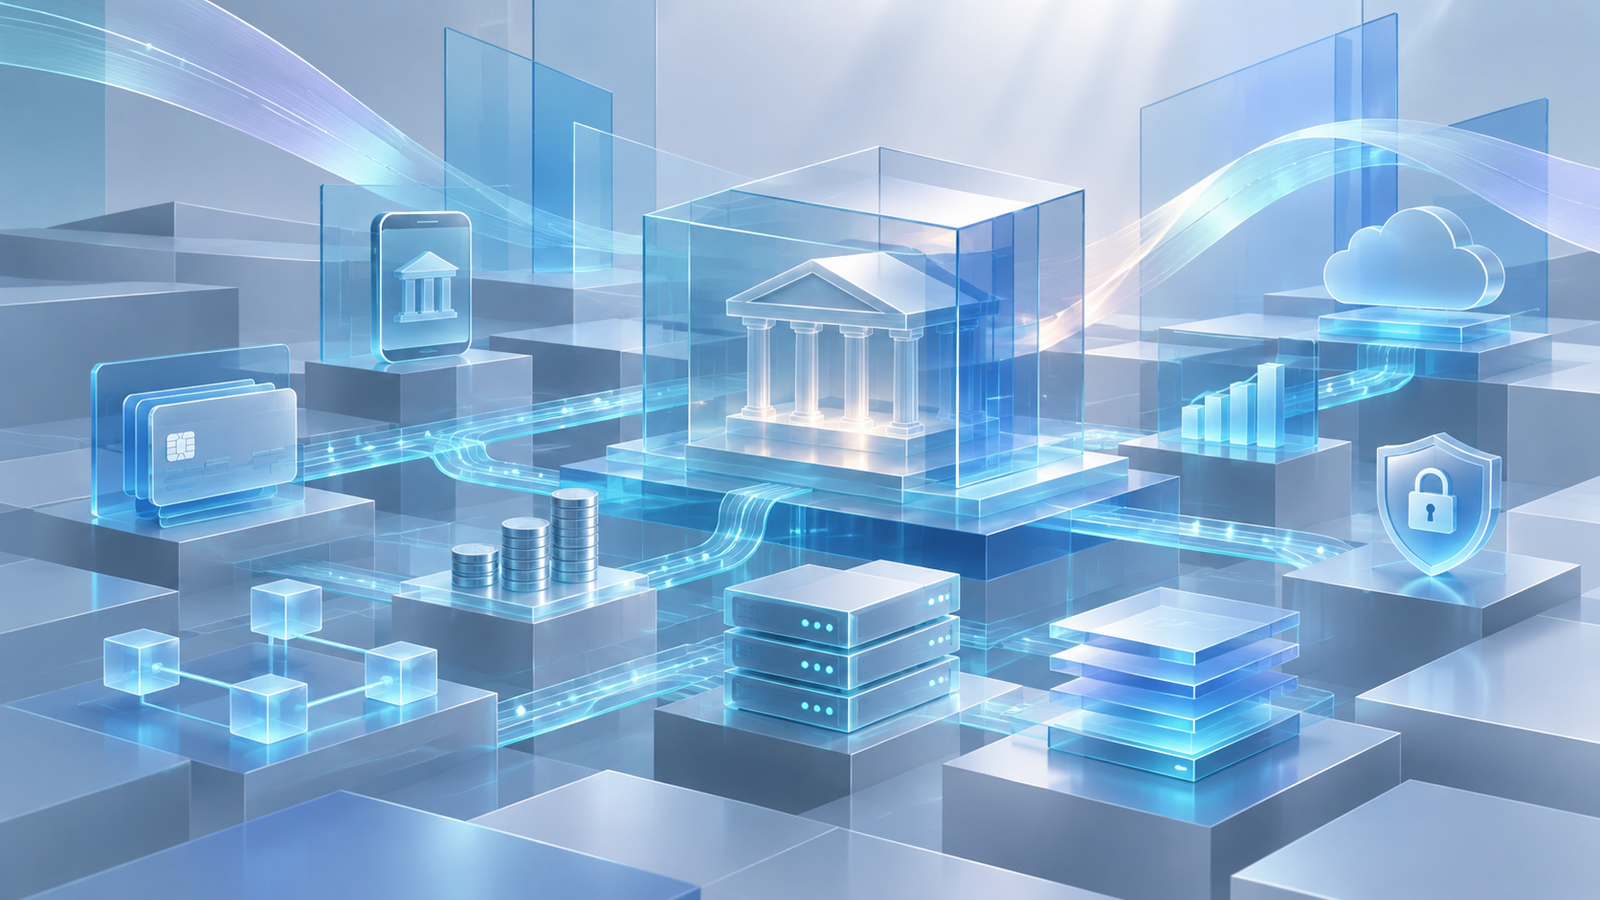
A composable banking system typically rests on three core layers, each with distinct responsibilities and independent scaling characteristics.
Channel Layer
The channel layer is the customer-facing interface: mobile apps, web portals, open banking APIs for third-party integrations, and agent tools. The goal is flexibility—consistent experiences across devices while keeping the user layer completely decoupled from backend systems. Product teams can evolve mobile features, add new channels, or adjust APIs without coordinating with core operations.
Service Layer
This is the heart of modularity. The service layer hosts microservices responsible for discrete business functions: loan origination, transaction management, compliance checks, fraud scoring, customer onboarding. Each service has its own data store when possible, its own deployment pipeline, and its own API contract. The service layer also includes the orchestration logic—a business process engine or workflow platform—that coordinates tasks across services, manages exceptions, enforces SLAs, and maintains the audit trail required by regulators.
Integration Fabric and Core Layer
Between the service layer and legacy systems sits the integration fabric: API gateways, event-streaming platforms (such as Kafka), and middleware. These technologies allow independent services to communicate asynchronously, maintain resilience under load, and trigger workflows without tight coupling. The core and legacy systems themselves—account management, settlements, compliance reporting—are wrapped with API facades or adapters, enabling them to interact with newer components without direct coupling.
This layered approach is not theoretical. Banks implementing it report faster iteration cycles because each layer can evolve independently. A payment service can be upgraded without revalidating the onboarding workflow. A new lending module can be added without touching account management. The result is a technology stack that adapts to business needs, not the reverse.
How Composable Banking Addresses Legacy Challenges
Legacy core banking systems rarely fail suddenly; they deteriorate slowly, accumulating technical debt, poor scalability, and brittle integration points that resist change. Composable architecture does not require rip-and-replace; it enables incremental modernization that reduces risk and preserves existing investments.
Breaking Monolithic Lock-In
Monolithic cores lock banks into a vendor's roadmap. Product enhancements depend on vendor releases; compliance updates require core patches; integrations with fintechs or open banking standards demand expensive customisation. Composable architecture breaks this cycle by allowing banks to swap modules independently. If a lending service is no longer competitive, it can be replaced with a better alternative without replacing the entire core.
Reducing Customisation Debt
Legacy cores often carry years of custom code layered on top of the vendor platform, making upgrades risky and expensive. Composable platforms are built to be extended through configuration and standard APIs, not customisation. New capabilities are added as independent services, not patches to the core. This dramatically reduces the cost and complexity of keeping the platform current.
Enabling Safe Experimentation
A monolithic core makes experimentation risky—testing a new product or process often means touching production logic. Composable architecture isolates experiments. Banks can deploy a test version of a new lending service in a sandbox, validate business impact, and roll back without affecting customers. This capability accelerates innovation cycles and reduces the cost of failed experiments.
Phased Migration Paths
Composable adoption does not require a big-bang replacement. A bank can start with an API gateway wrapped around the existing core, adding orchestration logic on top. As new services are built and deployed, legacy functions are gradually wrapped and exposed through APIs. Teams migrate components one at a time, running old and new versions in parallel, until the core is no longer needed. This phased approach spreads costs, reduces risk, and proves business value incrementally.
Business Benefits of Composable Platforms
The technical advantages of composable architecture translate into measurable business outcomes.
Faster Time-to-Market
Traditional core banking transformations take years to deliver. A composable approach enables financial institutions to launch new products in months. Instead of waiting for a full-stack upgrade cycle, product teams assemble existing capabilities and deploy as independent services. Banks report product launch cycles measured in weeks rather than quarters.
Lower Total Cost of Ownership
Composable platforms reduce operational overhead in multiple ways. First, cloud-native architecture enables elastic resource allocation—pay only for capacity you use, and scale automatically. Second, independent services can be maintained by smaller, focused teams rather than a large core support organisation. Third, reduced customisation and upgrade costs offset the investment in new architecture. Research shows composable approaches can deliver up to 50% lower TCO than legacy core systems over a five-year horizon.
Improved Agility and Resilience
When each service is independently deployable, teams move faster and reduce deployment risk. A failure in one service does not cascade across the system. Banking operations run on a microservices architecture where payment processing can continue even if the onboarding service has an issue. This resilience enables banks to maintain uptime and customer experience even during updates.
Scalability Without Redesign
As customer bases grow and transaction volumes increase, composable systems scale horizontally. New instances of a service spin up automatically based on demand. A surge in mobile onboarding does not starve lending services of resources. Each component scales independently based on its actual load, not on a monolithic core's generalised capacity planning.
Support for Open Banking and Ecosystem Integration
Open banking standards and embedded finance require integration with third-party services and data providers. Composable architecture is built for this. Open APIs make it simple to expose banking capabilities to partners, embed them into non-financial apps, or consume third-party services. This capability is increasingly essential as financial services blur into retail, telecom, and B2B platforms.
Implementation Approaches: Big Bang vs Phased Migration
The path to composable banking depends on business urgency, team capability, and risk appetite. Two broad strategies exist: big-bang replacement and phased modernisation.
Big-Bang Replacement
In this approach, a bank replaces the monolithic core entirely with a composable platform stack in one major project. The advantage is speed to a modern architecture. The risk is substantial: a single failure can disrupt the entire banking operation. This approach works for banks with greenfield operations (new banks, digital neobanks) but is rarely suitable for established institutions with complex legacy estates and decades of customer data.
Phased Modernisation (Recommended)
The phased approach minimises risk and proves value incrementally. It typically unfolds in stages:
- Stage One: Wrapping Legacy Systems. Deploy an API gateway and orchestration layer in front of the existing core, exposing core functionality through modern APIs. This step costs little and immediately enables third-party integrations and microservices to build on top.
- Stage Two: New Service Development. Build new digital capabilities as independent microservices—onboarding, lending, payments—connected through APIs. Run them in parallel with legacy systems, with orchestration routing requests intelligently between old and new.
- Stage Three: Gradual Migration. As new services prove stable and complete, migrate customer workloads incrementally. Run old and new versions side-by-side until legacy functionality is fully replaced. This parallel running period protects against regressions and gives teams time to validate new logic.
- Stage Four: Sunsetting Legacy Systems. Once all functionality is migrated, decommission the legacy core. Savings accrue: operational costs drop, support teams shrink, and innovation accelerates.
This staged approach spreads investment and risk. Banks achieve quick wins (stage one takes weeks, not months) while building confidence for later stages. Teams learn cloud-native development practices incrementally rather than all at once. And if a stage stalls, prior stages already deliver value.
Security, Compliance and Governance in Composable Systems
Modularity brings flexibility, but without strong governance, it can lead to fragmentation, inconsistent security controls, and regulatory gaps. Composable systems require deliberate governance architecture.
API Security and Access Control
In a composable ecosystem, every service exposes APIs that other services consume. This surface area must be rigorously controlled. Standard practices include mutual TLS authentication between services, OAuth 2.0 for user-facing APIs, and rate limiting to prevent abuse. Each service must validate inputs, log access, and enforce authorisation policies consistently. API gateways act as a policy enforcement point, centralising security rules and reducing the burden on individual services.
Data Governance and Privacy
Independent services often own their own data stores. Without clear governance, data can be duplicated, inconsistently updated, or exposed to the wrong services. Composable architectures require a data governance layer: a shared data catalogue, clear ownership of each data domain, and policies governing who can access what. GDPR and other privacy regulations mandate strong controls; composable systems must embed these by design, not bolt them on afterward.
Observability and Auditability
When services communicate across the network, failures become harder to diagnose. Composable systems require end-to-end observability: centralised logging, distributed tracing, and real-time metrics. Every transaction, every service-to-service call, every decision point must be logged and traceable. This visibility is essential for regulatory audits, incident investigation, and compliance reporting. Regulators increasingly expect banks to demonstrate that they can trace any customer action through their systems.
Service Registry and Configuration Management
As the number of services grows, teams risk losing track of dependencies, versions, and configurations. A service registry—a centralised catalogue of all services, their APIs, versions, and owners—is essential. Combined with version control and automated configuration management, this prevents rogue deployments and ensures consistency across environments.
Compliance by Design
Regulatory requirements—AML/KYC, GDPR, PSD2, MAS regulations—must be embedded into the architecture from the start, not added as afterthoughts. Composable systems achieve this by building compliance services as independent modules that all other services depend on. For example, a KYC service validates customer identity and sanctions screening for every account opening, payment, and lending decision. By centralising compliance logic, banks ensure consistency and reduce the risk of regulatory gaps.
Real-World Use Cases Across Banking Segments
Composable banking is not theoretical. Financial institutions across Europe and beyond are implementing modular architectures to solve specific business challenges.
Loan Origination Acceleration
A regional bank replaced its monolithic loan origination system with modular services for credit scoring, document verification, and compliance checks. Each service was independently deployable and could be upgraded without coordinating across teams. Time-to-decision dropped from 5 days to 4 hours. Loan officers could see real-time credit decisions and close deals faster. The modular approach also enabled the bank to swap in alternative credit scoring services from third-party providers, improving decision quality.
Digital Wallet Launch Without Core Replacement
A major telecom operator moving into financial services needed a digital wallet capability but could not replace its existing billing core, which processed millions of customer transactions daily. Using composable architecture, the operator deployed a wallet service independently, connected via APIs, and onboarded 500,000 users in 90 days without disrupting a single billing workflow. The wallet could scale independently based on usage, and new features were added continuously without coordinating with the core team.
Open Banking and API Ecosystem
Banks implementing open banking standards face the challenge of exposing internal capabilities through secure, standardised APIs while protecting the core system. Composable architecture makes this practical. Banks deploy an API gateway, expose banking capabilities through OpenAPI/Swagger standards, and third-party fintechs can instantly build on top. This ecosystem approach creates new revenue streams—embedded lending, payment processing, B2B2C services—without diverting core engineering teams.
Regulatory Reporting and Compliance
As compliance requirements multiply—stress testing, liquidity coverage ratios, AML reporting—banks struggle with monolithic cores that require expensive custom code for each new regulation. Composable architectures decouple compliance services. A bank can add a new reporting service without touching core systems. Data flows through an event backbone; reporting services subscribe to the data they need. New regulations translate into new microservices, not months of core customisation.
Frequently asked questions
Do we have to replace our entire legacy core to adopt composable banking?
No. A phased approach is both safer and more practical. Start by wrapping your existing core with an API gateway and orchestration layer. New digital capabilities can be built as independent microservices alongside the legacy system. Run old and new versions in parallel until legacy functionality is fully replaced. This staged migration spreads investment, reduces risk, and proves value incrementally.
What skills and team structure do we need for composable banking?
Composable banking demands modern software engineering practices. Teams need expertise in cloud-native development, microservices architecture, API design, containerisation (Docker, Kubernetes), and CI/CD automation. Organisational structure shifts too—from large core platform teams to smaller, autonomous squads owning specific services. Cultural change is often more challenging than technical change. Successful banks invest in training and hire engineers experienced in distributed systems and cloud infrastructure.
How do we ensure security and compliance across independent services?
Governance and observability are essential. Implement an API security policy enforced at the gateway level; use mutual TLS and OAuth 2.0 for service-to-service and user-facing APIs. Embed compliance logic as independent services that all others depend on. Centralise logging and tracing so every transaction is auditable. Maintain a service registry and clear ownership models. Regulators expect banks to demonstrate end-to-end visibility; composable systems, properly governed, actually make this easier than monolithic cores.
What is the typical business case and ROI for composable banking?
The financial impact depends on your current state and business goals. For banks modernising legacy cores, savings typically come from lower operational costs (smaller support teams, elastic infrastructure), faster product launches (reduced time-to-market), and new revenue streams (open banking, embedded finance). Research suggests composable approaches can deliver 30–50% lower total cost of ownership and 50–70% faster product deployment cycles compared to traditional core transformations. The tradeoff is upfront investment in architecture, tooling, and team training—typically a 2–3 year payback period for large institutions.